
Wexford Insurance Hires Max Baker to Expand Its Small Business Insurance Practice
Wexford Insurance, a national independent insurance agency based in Indiana, has hired Max Baker to help expand its small business insurance practice.
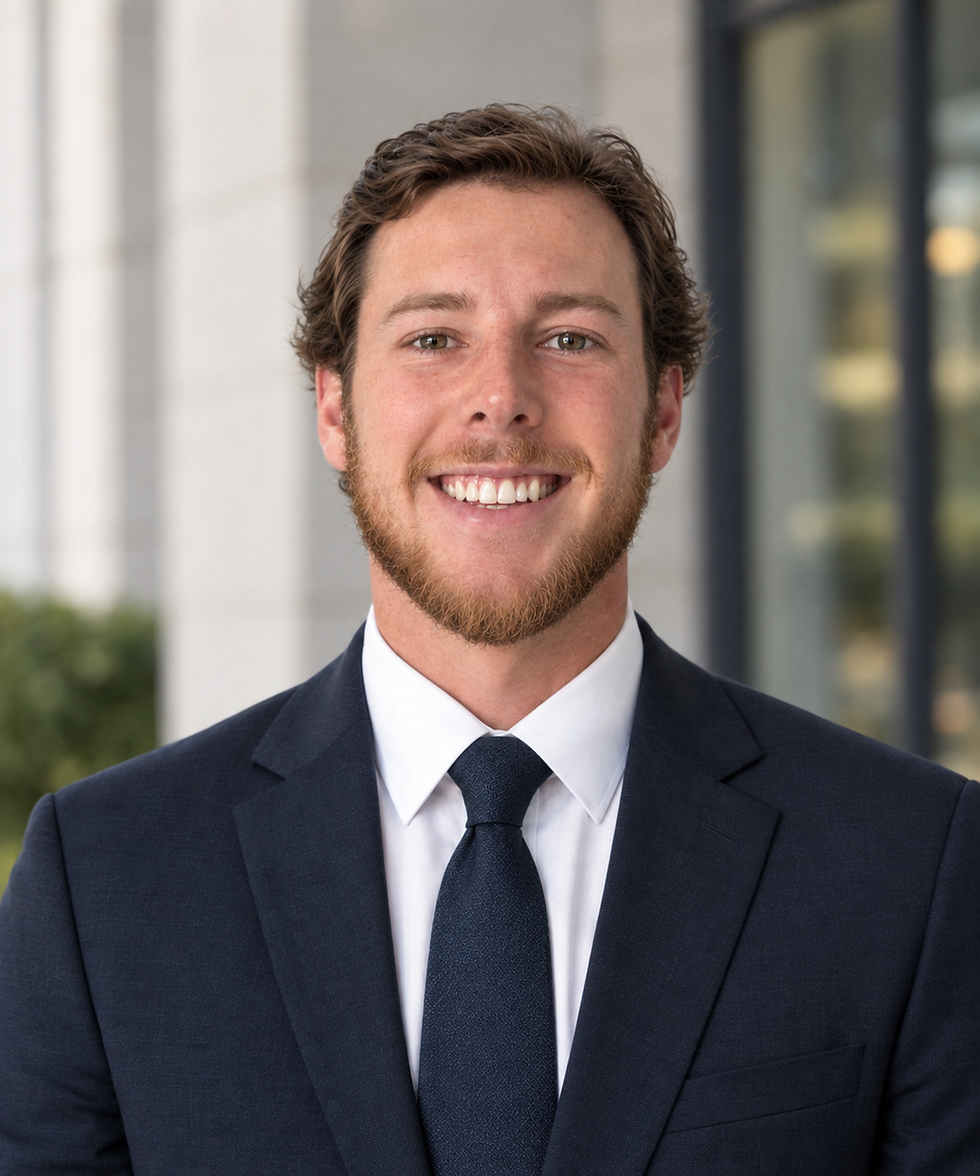
Max Baker joins the growing Wexford team after working as a business insurance agent with State Farm. In his new role as Regional Sales Director, he will focus on helping contractors, manufacturers, and other small-business owners evaluate commercial insurance based on their actual operations.
The move gives Max Baker an opportunity to work within an independent agency that represents multiple insurance companies. Rather than working within the products and underwriting requirements of one primary insurance carrier, he can now help eligible clients explore coverage through a broader selection of available commercial insurance markets.
For business owners, this can be especially important when their company has specialized operations, experiences rapid growth, or falls outside the underwriting preferences of a particular insurance provider.
Expanding Wexford Insurance’s Small Business Practice
Wexford Insurance works with business owners throughout the country while maintaining its home office in Indiana.

Its small business clients range from one-person companies purchasing commercial insurance for the first time to established contractors and manufacturers with employees, vehicles, equipment, property, and operations in multiple states.
The addition of Max Baker gives these businesses another dedicated sales professional who understands commercial insurance and the pressures owners face when requesting quotes.
Many small-business owners contact an insurance agency because they are dealing with an immediate need. They may be:
Starting a new business
Signing a customer contract
Purchasing equipment
Hiring their first employees
Adding commercial vehicles
Opening another location
Expanding into a new state
Responding to a premium increase
Approaching an insurance renewal
Addressing a certificate requirement
Looking for an insurance market that better understands their industry
A responsive agent must identify why the owner needs coverage, determine what information insurance companies will require, and help move the submission forward efficiently.
Max Baker’s previous commercial insurance experience gives him a foundation for supporting these conversations. At Wexford Insurance, he can combine that experience with the agency’s independent market access and industry-specific approach.
Moving From a Captive Environment to an Independent Agency
A captive insurance agent generally represents one primary insurance company and offers the products available through that organization. An independent agency represents multiple insurance companies and can evaluate available options from different markets.
This does not automatically mean that one distribution model is appropriate for every customer. A captive insurance company may offer competitive products for businesses fitting its underwriting appetite. The potential limitation occurs when the company’s operations, claims history, equipment, property, vehicles, or industry do not align with that insurer’s requirements.
Max Baker decided to join Wexford Insurance in part to expand the available insurance markets he could access for business owners.
That expanded access is valuable in commercial insurance because no single insurance company is the right fit for every contractor or manufacturer.
An insurance company that is competitive for an electrical contractor may not be interested in an excavating business. A carrier that works well for a small metal manufacturer may not be the appropriate market for a pallet manufacturer, plastics operation, or food processor.
Insurance company appetites can also change. An insurer may adjust its pricing, geographic availability, preferred business classifications, property requirements, vehicle restrictions, or acceptable claims history.
Working through an independent agency gives the agent an opportunity to evaluate more than one available market when appropriate.
Wexford Insurance describes its independent model as representing numerous insurance companies rather than being tied to one carrier, allowing the agency to approach available markets according to each client’s individual circumstances.
Helping Contractors Protect Their Businesses
One of Max Baker’s primary areas of focus will be contractor insurance.
Contractors face risks that can vary significantly depending on the work they perform. A general contractor, excavation contractor, electrician, plumber, concrete contractor, roofer, landscaper, and HVAC company should not all be evaluated as if their operations are identical.
An agent working with a contractor needs to understand details such as:
The specific work the company performs
Whether the business works on residential or commercial projects
The percentage of work subcontracted to others
Whether subcontractors provide insurance certificates
The company’s annual revenue and payroll
The states in which work is performed
The types of vehicles and equipment used
Whether the contractor performs excavation or underground work
The maximum height or depth at which employees work
Whether the company works on new construction or existing structures
The size and scope of completed projects
Contractual insurance requirements
The history of insurance claims
These details can affect insurance eligibility, classifications, premiums, required endorsements, and available coverage.
Max Baker will help contractors identify the information relevant to their operations and prepare submissions for available insurance companies.
Common Insurance Coverages for Contractors
Insurance requirements vary by contractor, project, state, and customer contract. However, contractors commonly evaluate several types of commercial coverage.
General Liability Insurance
Commercial general liability insurance may respond to certain claims alleging bodily injury, property damage, personal injury, or advertising injury, subject to the policy’s terms, limits, and exclusions.
Contractors should carefully review whether their policy addresses their described operations, subcontracted work, completed operations, and contractual requirements.
Workers’ compensation generally provides covered benefits for occupational injuries and illnesses according to applicable state requirements and policy terms.
Employee duties, payroll, state of employment, classifications, safety practices, and claims history may affect eligibility and cost.
Commercial Auto Insurance
Contractors often use pickup trucks, service vehicles, vans, dump trucks, or other commercial vehicles to transport employees, tools, materials, and equipment.
Commercial auto insurers may review vehicle types, driver records, travel radius, garaging locations, vehicle use, prior claims, and safety procedures.
Contractors may own tools and mobile equipment that travel between job sites. Inland marine or contractor equipment coverage may help address certain covered losses involving property that is mobile or located away from the primary business premises.
Commercial Umbrella or Excess Liability
Umbrella or excess liability insurance may provide additional limits above designated underlying policies.
Contractors may need higher limits to satisfy project contracts, qualify for certain jobs, or address the scale of their operations.
Some contractors need license, permit, bid, performance, payment, or other surety bonds. Bond requirements depend on the project, governing authority, customer, and type of work performed.
Max Baker will work with contractors to evaluate the coverages relevant to their specific businesses rather than relying on a generic insurance package.
Supporting Manufacturing Businesses
Max Baker will also focus on helping manufacturers evaluate commercial insurance.
Manufacturing accounts require careful attention because operations differ considerably from one company to another. The raw materials used, products manufactured, machinery operated, workforce, building characteristics, customer contracts, and distribution methods can all affect the insurance program.
Important underwriting considerations may include:
The products being manufactured
Raw materials and production processes
Machinery and equipment values
Building construction and age
Electrical, sprinkler, and fire-protection systems
Dust, fumes, chemicals, or combustible materials
Quality-control procedures
Product testing and documentation
Employee duties and safety training
Commercial vehicle and delivery exposures
Domestic and international distribution
Customer concentration
Product recall procedures
Loss history and corrective actions
Business interruption risks
Supply-chain dependencies
A manufacturer may need an agent who can accurately explain the operation to underwriters. An incomplete or unclear description can lead to delays, inaccurate classifications, unsuitable quotes, or difficulty locating interested insurance companies.
Max Baker’s role will include learning how each manufacturer operates, organizing the relevant information, and helping the business approach available insurance markets.
Common Insurance Coverages for Manufacturers
Although each operation requires an individual review, manufacturers may need to evaluate the following coverage areas.
Commercial General Liability
General liability may address certain third-party injury and property damage claims. Manufacturers should review how the policy treats premises, ongoing operations, products, and completed operations.
Product Liability Insurance
Product liability is a significant consideration for many manufacturers. Claims may allege that a product caused bodily injury or property damage because of a defect, failure, or improper warning.
The type of product, its intended use, where it is sold, and the loss potential can all influence underwriting.
Commercial Property Insurance
Commercial property insurance may cover buildings, machinery, business personal property, raw materials, and finished inventory against covered causes of loss.
Manufacturers should evaluate whether reported values accurately reflect the cost to repair or replace essential buildings and equipment.
Business Income and Extra Expense
Damage to a building or critical machine can interrupt production and revenue. Business income and extra expense coverage may help address certain financial consequences of a covered interruption, depending on policy terms.
Manufacturers should consider how long it may take to repair specialized equipment, replace machinery, obtain permits, restore utilities, or relocate production.
Equipment Breakdown Insurance
Equipment breakdown coverage may address certain covered mechanical, electrical, or pressure-system failures that may not be handled by a standard property policy.
Workers’ Compensation
Manufacturing employees may work around machinery, forklifts, production lines, heat, chemicals, sharp materials, repetitive processes, and lifting exposures.
Insurers may evaluate employee training, machine guarding, personal protective equipment, written safety procedures, and prior injury trends.
Commercial Auto Insurance
Manufacturers using company vehicles for deliveries, sales, service, or product transportation may require commercial auto coverage.
Commercial Umbrella or Excess Liability
Manufacturers may purchase excess limits because of contractual requirements, product exposures, company size, or the potential severity of a liability claim.
Coverage availability and recommendations depend on the individual manufacturing operation and the terms offered by available insurers.
Industry Knowledge Can Improve the Insurance Process
Contractors and manufacturers may experience frustration when an insurance professional does not understand the business being insured.
The business owner may spend considerable time explaining basic operations before the agency can determine what information is relevant. That can delay the quoting process and create uncertainty about whether the submission accurately represents the company.
Wexford Insurance has built its commercial practice around specialization. Rather than approaching every company as a generic small business, its team works to understand the industries and operational details that influence insurance underwriting.
This is the environment Max Baker joins as he develops his contractor and manufacturing practice.
The objective is not to eliminate underwriting questions. Insurance companies still require accurate information to evaluate a business. The objective is to ask relevant questions, organize the information effectively, and avoid creating unnecessary work for the business owner.
National Capabilities With Personal Service
Although Wexford Insurance is located in Indiana, it serves clients throughout much of the United States.
Its digital model allows contractors, manufacturers, and other business owners to find the agency online, learn about relevant insurance considerations, and connect with a professional who understands their industry.
That national reach does not replace personal service.
Clients still work with actual sales professionals and account managers. They can explain their operations, discuss coverage questions, review insurance proposals, and request assistance as their businesses change.
Max Baker adds another experienced commercial insurance professional to that team.
His focus will be straightforward: learn how the business operates, identify relevant coverage considerations, gather the information required by insurers, and help the owner evaluate available options.
What Business Owners Can Expect When Working With Max Baker
A contractor or manufacturer working with Max Baker can expect a process centered on the business rather than a one-size-fits-all insurance product.
The process may include:
Learning about the company’s operations and insurance goals
Reviewing its current insurance program when available
Identifying relevant coverage needs and contract requirements
Gathering required underwriting information
Determining which available insurance markets may consider the account
Requesting and reviewing insurance proposals
Explaining material differences in coverage, limits, deductibles, and pricing
Assisting with the transition when the owner selects an option
Supporting the account as the company grows or changes
Not every business will qualify for every insurance company or program. Quotes, coverage, pricing, and availability depend on the company’s operations, location, claims history, safety practices, property, vehicles, workforce, and other underwriting factors.
Wexford Insurance Continues Investing in Commercial Insurance Talent
The hiring of Max Baker is part of Wexford Insurance’s continued investment in its national commercial insurance practice.
The agency’s publicly listed team includes professionals with backgrounds in commercial insurance, underwriting, risk management, customer experience, operations, logistics, financial services, human resources, and business development. Max Baker is listed as a Regional Sales Director focused on helping contractors and business owners build coverage aligned with how their companies operate. [wexfordins.com]
By adding professionals with commercial insurance and business experience, Wexford Insurance intends to increase its capacity without losing the personal communication expected from a privately owned agency.
For Max Baker, joining an independent agency creates a broader opportunity to serve businesses whose needs may require access to different insurance companies and underwriting approaches.
For Wexford’s clients, it means another dedicated professional is available to help navigate commercial insurance.
Contact Max Baker at Wexford Insurance
Contractors, manufacturers, and other small-business owners interested in working with Max Baker can contact Wexford Insurance to discuss their operations and insurance needs.
Max Baker, Regional Sales Director Phone: 317-766-0801 Email: mbaker@wexfordins.com
Business owners can also call Wexford Insurance at 317-942-0549 or visit the agency’s Our People page to learn more about its commercial insurance team.
Insurance eligibility, coverage, premiums, limits, deductibles, and availability vary by insurer, state, business operation, claims history, and individual risk characteristics.


